Download Our Guide for Haulage Businesses to Understand Operational Risks - ‘Moving Goods & Managing Risk’

Category: Uncategorized

  • Insuring Startups & Early-Stage Businesses: What You Need, What You Don’t

    Insuring Startups & Early-Stage Businesses: What You Need, What You Don’t

    Startup insurance advice can feel like an all-or-nothing checklist when you’re setting up a new business – buy everything now, just in case. For a business working with limited capital, that’s not always realistic, and it isn’t actually necessary. The more useful question isn’t “what insurance exists?” but “what does my business genuinely need from day one, and what can wait until it’s actually relevant?”

    What Every Early-Stage Business Actually Needs From Day One

    A handful of covers matter from the moment you start trading, regardless of sector:

    •      Employers’ Liability is a legal requirement the moment you employ anyone – including casual staff, part-time help or certain contractors working under your direction. There’s no grace period for a new business; if you have people working for you, you need it in place.

    •      Public Liability covers claims if your business causes injury or property damage to a third party – a client tripping in your office, damage caused during a site visit, a customer at a pop-up stall. If you have any physical presence with the outside world, this is a day-one cover, not a “grow into it” one.

    •      Professional Indemnity matters from your very first piece of paid advice, design or specification work – not once you’ve built a track record. A claim can arise from work carried out in your first month just as easily as your fifth year, and cover generally can’t be backdated once a claim has emerged.

    •      Cyber Insurance has become an early-stage essential rather than an add-on, simply because most startups run on cloud tools, hold some customer data and take payments online from day one – often before there’s a dedicated IT function in place to manage the risk internally.

    What Can Usually Wait

    Just as some cover is essential immediately, other cover can genuinely be built up as the business grows:

    •      Extensive property and stock cover – if you’re working from home, a co-working space or a small rented unit with limited equipment, a large sums-insured property policy isn’t yet proportionate. Revisit this as you invest in premises, stock or equipment.

    •      Directors’ & Officers’ insurance – often more relevant once you take on external investors or non-executive directors, rather than at the earliest founder-only stage.

    •      Business Interruption with a long indemnity period – valuable once you have established trading income to protect, less critical before you have a consistent revenue baseline to measure against.

    •      Fleet insurance – only relevant once you actually own or lease vehicles; there’s no need to pay for cover ahead of the asset.

    Sector-by-Sector: What “Day One” Actually Looks Like

    Readhunt works with early-stage and growing businesses across construction, haulage & transport, manufacturing, logistics and civil engineering – and what’s essential on day one looks a little different in each:

    Construction & Contractors – even as a brand-new subcontractor, your first contract will likely specify minimum Public Liability limits matching your main contractor’s, and modern JCT and NEC contracts carry detailed insurance obligations from the outset. Getting this wrong before you’ve won your first job can delay – or lose – the contract.

    Haulage & Transport / Logistics – from your very first load, Goods in Transit cover is separate from motor fleet insurance and needs arranging alongside it, not after. A new haulage or logistics startup that assumes fleet cover extends to cargo is exposed from week one.

    Manufacturing – Product Liability becomes relevant the moment you ship your first product, however small the run. Machinery Breakdown and longer Business Interruption periods tend to matter more as capital equipment investment grows.

    Civil Engineering & design-led startups – Professional Indemnity is the priority from the very first design signed off, because civil engineering liability can surface years after a project completes – long after a young business might assume the risk had passed.

    Professional & tech-enabled startups – for consultancies, agencies and digital businesses, Professional Indemnity and Cyber Insurance are typically the two covers that matter immediately, with property and fleet cover rarely relevant this early.

    A Simple Way to Think About It

    Four questions cut through most of the noise for a new business:

    1.     Do you have anyone working for you, even casually? → Employers’ Liability is required.

    2.     Do you meet clients, visit sites, or have any physical presence? → Public Liability matters.

    3.     Do you give advice, design something, or specify a solution? → Professional Indemnity matters.

    4.     Do you hold digital data or take online payments? → Cyber Insurance matters.

    Everything else is a conversation to have as it becomes relevant to how the business is actually operating – not a box to tick before you’ve traded a single day.

    Insurance Isn’t Just Protection – It’s Contract-Readiness

    For many early-stage businesses, particularly in construction, manufacturing and logistics, insurance isn’t only about risk transfer – it’s part of winning work. Larger clients and principal contractors increasingly expect evidence of appropriate cover as a condition of appointment, and government guidance on public sector procurement has specifically encouraged buyers to make the process more accessible to smaller suppliers – provided those suppliers can demonstrate the right insurance is in place when it’s needed. Getting the essentials right early isn’t just protection; it’s part of being ready to compete.

    Review As You Grow

    The insurance a business needs in month one rarely matches what it needs at month eighteen. As headcount, turnover, premises and contracts change, cover should change with them – something worth revisiting at every renewal rather than assuming last year’s policy still fits. According to the British Insurance Brokers’ Association (BIBA), regular broker engagement – not just at renewal – is one of the clearest ways smaller businesses keep pace with a changing risk profile, and the Association of British Insurers (ABI) makes a similar point about the value of proportionate, regularly reviewed cover for growing SMEs.

    Talk To Readhunt

    At Readhunt, we work with early-stage and growing businesses across construction, haulage, manufacturing, logistics and engineering to build insurance programmes that match where the business actually is – not where a generic checklist assumes it should be.

    This is a journey we know well – Readhunt has partnered early-stage businesses from that very first policy through years of growth, and we’d be glad to walk the next stage of yours with you.

    If you’re setting up a new business and want a clear, no-obligation steer on what’s essential now and what can wait, get in touch on 01709 278178 or email insurance@readhunt.co.uk.
  • Meet the Team: Olivia Haynes – Building Expertise in the London Market

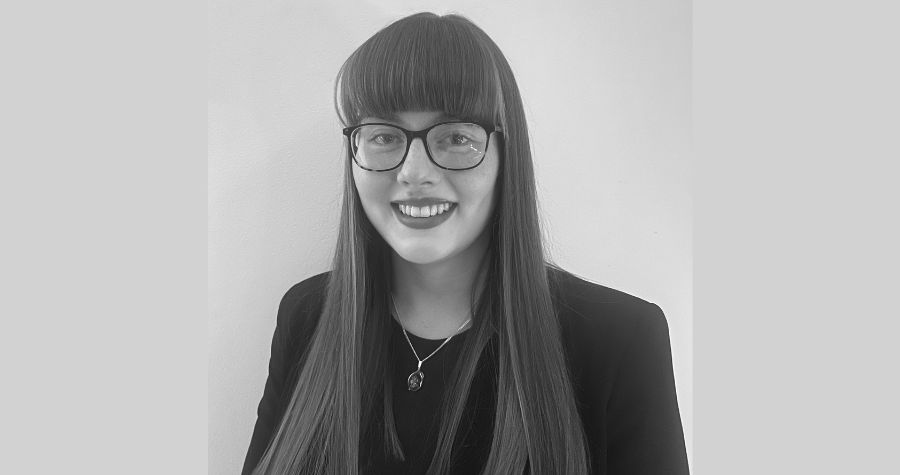
    Meet the Team: Olivia Haynes – Building Expertise in the London Market

    At Readhunt we believe our greatest strength is our people. Behind every successful placement is someone committed to understanding clients, building relationships and finding the right solution. In our Meet the Team series, we’re introducing the people who make that happen.

    This month, we’re catching up with Olivia Haynes, Senior Account Handler.

    At just 21, Olivia has already achieved something many aspire to much later in their careers – she has completed her London Market Cert CII qualifications (LM1, LM2 and LM3), bought and renovated her first home, and developed specialist expertise in one of the most technical areas of commercial insurance.

    Growing up in Rochford, Essex, Olivia studied Business, Economics and English Literature at A level before discovering a career in insurance through school work experience with a local broker.

    “I originally wanted to become a solicitor,” she laughs, “but once I experienced the insurance industry, I realised how varied it is and how much I enjoyed helping businesses solve complex problems.”

    After leaving sixth form, Olivia joined Citynet Insurance Brokers, where she worked within the Professional Indemnity team, developing expertise across Financial Lines, including Professional Indemnity, Directors’ & Officers’ Liability and Cyber Insurance.

    She joined Readhunt in June 2025 and now manages all of the team’s Financial Lines policies, supporting brokers and clients with specialist placements through the London insurance market.

    For Olivia, success isn’t measured purely by policies placed – it’s about building lasting relationships.

    “Success is having brokers who genuinely want to work with you because they know they’ll receive a high level of service, clear communication and a personal approach.”

    That relationship-led mindset is something she believes is fundamental to both her own role and the future success of the London Market’s team.

    “The London Market is built on relationships. Strong communication with brokers and underwriters is essential to achieving the best possible outcome for every client.”

    Olivia describes herself as dedicated, meticulous and resourceful, while colleagues would probably choose diligent, conscientious and reliable – qualities reflected in her meticulous attention to detail and determination to secure the best result for every client.

    Outside work, Olivia’s ambition continues. Having recently bought and renovated her first home, she’s already working towards her long-term goal of building a property portfolio.

    When she’s not renovating or researching property, you’ll often find her reading – a passion that’s stayed with her since studying English Literature.

    Looking ahead, Olivia is excited to continue supporting the growth of Readhunt and Heritage London Markets, helping brokers navigate increasingly complex risks while continuing to build the trusted relationships that underpin every successful placement.

  • Construction Insurance Claims : Why Project Delays Cost More Than the Damage

    Construction Insurance Claims : Why Project Delays Cost More Than the Damage

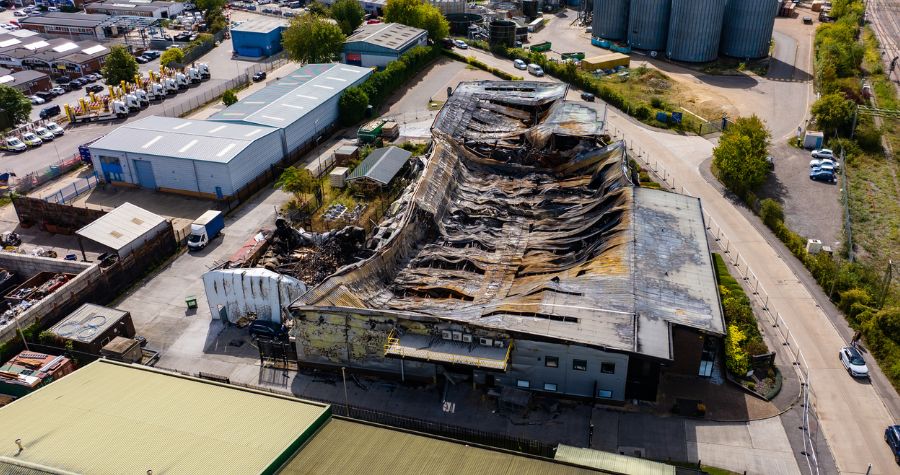
    When most people picture construction insurance claims, they picture damage – a fire on site, a flood through unfinished works, a theft of plant or materials. But for many contractors, the physical loss is not what actually hurts the business. It’s the delay that follows.

    A stalled project doesn’t just pause work. It sets off a chain reaction: contract penalties for missed deadlines, labour standing idle on the payroll, hired equipment racking up costs while it sits unused, disputes with clients over timelines, and – often the most damaging of all – the loss of the next contract because the business couldn’t move on to it. Add these together and the financial impact of a delay can easily outstrip the cost of the original damage.

    The Question Contractors Should Really Be Asking

    “Are we insured?” is the wrong starting point. The better question is: if something happened on site tomorrow, how quickly could we recover and get back to work?

    That single question shifts the focus from the policy document to the process behind it – how a claim is handled, how fast a loss adjuster is instructed, how quickly funds are released, and how proactively a broker manages the claim rather than simply processing it. For SME contractors in particular, where cash flow and reputation are tightly linked to delivery dates, this can be the difference between a difficult few weeks and a genuinely damaging year.

    Why Risk Management Matters as Much as the Policy

    Robust risk management – from site security and fire prevention to contractual protections against delay-related loss – reduces the likelihood of a claim in the first place. But no risk management plan removes the possibility entirely, which is why claims support has to be considered part of the same conversation, not an afterthought once cover is in place.

    According to the British Insurance Brokers’ Association (BIBA), specialist broker involvement – particularly at the point of claim – is one of the clearest ways SMEs can improve outcomes and speed of resolution, since brokers can advocate on the client’s behalf rather than leaving the business to navigate the process alone. The Association of British Insurers (ABI) similarly highlights that construction remains one of the more complex sectors for claims handling, given the number of parties, contracts, and interdependencies typically involved on a single project.

    For SME contractors weighing up cover, the British Business Bank also notes that resilience planning – including adequate insurance and access to working capital during disruption – is a recurring factor in which smaller construction businesses recover fastest from unexpected setbacks.

    Building Recovery Into the Plan, Not Just the Policy

    The businesses that recover fastest from a construction claim are rarely the ones with the biggest policy limits. They’re the ones who went into the process with a broker who understood their contracts, their supply chain, and their appetite for risk – and who treated claims support as part of the relationship, not a separate transaction after something goes wrong.

    That’s the conversation worth having before the damage happens, not after.

    Readhunt works with SME contractors across the UK to build insurance programmes around how a business actually operates on site – not just what it owns. 

    Get in touch with our team to discuss your insurance and project risk.

  • Meet the Team: Mike Huntington

    Meet the Team: Mike Huntington

    Building Readhunt on Relationships, Trust and Doing Right by Clients

    Some businesses are built around products. Others are built around people.

    For Mike Huntington, founder of Readhunt and now Consultant and Account Director, it’s always been the latter.

    After nearly four decades in the insurance industry and more than 20 years building Readhunt into a respected independent brokerage, Mike still believes the fundamentals of good insurance advice haven’t changed.

    People buy from people.

    Building Readhunt

    Mike’s insurance career began in 1986, straight from school, at East Mills Insurance – a fitting starting point, with offices directly opposite the building that would later become home to Readhunt.

    Reflecting on his journey, Mike says:

    “There’s a nice symmetry to my career. I started out in 1986, straight from school, at a broker whose office sat directly across the road from where Readhunt would later have its home. I had no idea then that I’d one day build my own firm on the very same street. It’s a reminder that you don’t always need to go far to build something of your own – you just need to do it properly.”

    Over the following 16 years, Mike gained experience with both insurers and brokers, including Eagle Star and Ward Evans, developing a deep understanding of commercial insurance, client service and business development.

    By 2002, he felt there was a better way.

    “I’d spent years seeing how different brokers operated and believed I could do it better – and, more importantly, better for the client.”

    That belief led to the creation of Readhunt.

    Over the next 22 years, Mike built the business around long-term relationships, honest advice and exceptional client service. In October 2024, Readhunt became part of SRT & Partners, with Mike remaining as Account Director to continue supporting clients and helping shape the next chapter of the business.

    “I still love what I do.”

    Relationships Come First

    Ask Mike what success looks like and the answer isn’t turnover or growth targets.

    It’s clients who stay with Readhunt for years because they trust the advice they receive.

    It’s being the first phone call when something changes.

    And it’s recommendations that come naturally because clients know they’ll be looked after.

    “If we continue winning good new business and looking after the clients we’ve already got, the growth takes care of itself.”

    Experience That Makes a Difference

    With almost 40 years in the industry, Mike’s greatest strength isn’t simply his technical knowledge.

    It’s building genuine, long-lasting relationships where clients always know where they stand.

    That philosophy continues to shape the culture at Readhunt today.

    Looking Ahead

    Mike believes the future of Readhunt will continue to be defined by the same values that built the business in the first place.

    “The client is always the priority. If clients trust us, everything else follows.”

    It’s a simple philosophy – but one that has stood the test of time.

    Outside of work, Mike enjoys travelling and spending time with his five-year-old son, who, in his own words, “certainly keeps me on my toes.” More recently, he’s also installed a home gym and admits he’s now “trying to justify its existence!” It’s another reflection of Mike’s practical approach – whether in business or outside it, if something’s worth doing, it’s worth committing to.

  • Why Claims Handling Is the True Test of Your Commercial Insurance Broker

    Why Claims Handling Is the True Test of Your Commercial Insurance Broker

    When choosing commercial insurance, it’s easy to compare premiums, policy limits and renewal dates. But the true value of your insurance isn’t measured when you buy the policy – it’s measured when you need to make a claim.

    Whether it’s a fire, flood, theft, cyber incident or liability claim, the way your broker supports you can have a significant impact on how quickly your business recovers.

    Why commercial insurance claims are becoming more challenging

    UK businesses are operating in an increasingly complex risk environment. Inflation has pushed up repair and reinstatement costs, supply chain delays continue to affect replacement times, and extreme weather events have led to rising property insurance claims across the UK. At the same time, insurers are placing greater emphasis on accurate valuations and effective risk management when assessing claims. Source: Insurance Business Magazine.

    Recent changes in employment legislation, including the Worker Protection (Amendment of Equality Act 2010) Act 2023, have also increased employers’ responsibilities to proactively manage workplace risks. This reinforces the importance of having appropriate Employers’ Liability and Management Liability insurance in place, alongside specialist advice from an experienced broker.

    Why your insurance broker matters during a claim

    Many businesses assume their insurer manages the claims process from start to finish. In reality, your insurance broker plays a vital role in ensuring the claim progresses smoothly.

    An experienced broker will:

    • Notify insurers promptly
    • Gather the necessary evidence
    • Liaise with insurers and loss adjusters
    • Keep you informed throughout the process
    • Help resolve issues quickly
    • Work to minimise disruption to your business

    Having an experienced adviser managing the process allows business owners to focus on keeping their operations running while someone else deals with the complexities of the claim.

    Readhunt’s approach to claims

    At Readhunt, we believe claims handling is one of the most important services we provide.

    Our dedicated claims team supports clients from the first notification of loss through to final settlement, ensuring every enquiry is acknowledged within 24 hours or less. We work closely with insurers, loss adjusters and third parties to secure the best possible outcome while keeping clients updated every step of the way.

    Our reputation has been built on providing proactive, personal support when businesses need it most.

    One long-standing manufacturing client said:

    “It was particularly helpful when we were faced with the need to claim following a significant fire incident.”

    Another client commented that Readhunt helped them navigate a claim, making the entire process “smooth and stress-free.”

    Across all our client testimonials, the same themes emerge – responsive communication, genuine care, technical expertise and a team that takes the time to understand each client’s business before a claim ever happens.

    Specialist claims expertise for specialist industries

    Claims look very different depending on your sector, which is why specialist knowledge matters.

    For construction businesses, claims can involve contract works, plant and machinery, professional liabilities and project delays.

    For manufacturers, machinery breakdown, business interruption and property damage can have a significant financial impact if not managed quickly.

    For haulage and logistics operators, vehicle damage, goods in transit claims and fleet incidents require prompt action to reduce downtime and keep businesses moving.

    Because Readhunt works with businesses across these specialist sectors every day, we understand the operational pressures involved and can help clients navigate even complex claims with confidence.

    Preparing for a successful claim

    One of the best ways to improve the outcome of a future claim is to prepare before anything goes wrong.

    Regular insurance reviews, accurate sums insured, effective risk management and policies that reflect your changing business all help ensure claims are handled efficiently and reduce the risk of underinsurance.

    At Readhunt, we work with clients throughout the year – not just at renewal – to ensure their insurance programme continues to provide the right level of protection as their business evolves.

    More than an insurance policy

    Anyone can arrange insurance.

    The real difference becomes clear when your business experiences an unexpected event.

    At Readhunt, we’re committed to standing alongside our clients before, during and after a claim, providing expert guidance, proactive communication and personal support every step of the way.

    If you’d like to review your commercial insurance or understand how your current broker would support you in the event of a claim, we’d be delighted to help.

    Contact Readhunt today for a free, no-obligation insurance review and discover the difference specialist claims support can make.

  • Resilience Only Matters When It’s Tested: What the UK Heatwave Reveals About Business Risk

    Resilience Only Matters When It’s Tested: What the UK Heatwave Reveals About Business Risk

    As the UK heatwave is delivering sustained record temperatures, many businesses are being reminded that risk does not always arrive in obvious or dramatic ways.

    For organisations operating in specialist sectors, extreme heat can quietly disrupt operations. Overheating machinery, increased fire risk, product spoilage, workforce wellbeing concerns, and unplanned downtime can all affect productivity and profitability.

    Which highlights a simple but often overlooked truth:

    Insurance is rarely top of mind—until it becomes essential.

    Extreme Weather Is Becoming a Business Constant, Not an Exception

    Heatwaves in the UK are becoming more frequent and more intense. The Met Office has consistently highlighted the increasing likelihood of extreme temperature events as part of long-term climate trends.

    For businesses, this means operational planning and risk transfer need to evolve accordingly.

    Manufacturing facilities, warehouses, engineering operations, construction sites, and logistics businesses are particularly exposed. High temperatures can cause equipment stress, increase fire risk, and reduce efficiency across critical systems.

    The Real Cost of Disruption

    When operations are interrupted, the impact is rarely limited to physical damage.

    Businesses often experience:

    • Lost revenue from halted production or services
    • Delayed customer deliveries and contractual penalties
    • Increased operating costs during recovery
    • Supply chain disruption
    • Damage to customer relationships and reputation
    • Cashflow pressure during downtime

    The UK Government’s guidance on business continuity planning highlights that many organisations underestimate the time and cost required to recover from disruption, particularly where critical equipment or premises are affected.

    Why Specialist Sectors Face Specialist Risks

    One of the most common challenges in commercial insurance is the assumption that “standard cover” will respond as expected in a complex loss scenario.

    However, businesses evolve faster than their insurance programmes.

    Plant investment increases. Revenue grows. Operations expand across multiple sites. Supply chains become more interdependent. Yet insurance arrangements are not always reviewed at the same pace.

    This is especially relevant for sectors such as:

    • Manufacturing and engineering
    • Construction and infrastructure
    • Logistics and distribution
    • Property investment and development
    • Specialist trade and services

    In these environments, the detail matters: sums insured, business interruption periods, reinstatement conditions, and machinery breakdown cover can all significantly influence recovery outcomes.

    Insurance Is Only One Part of Resilience

    Effective risk management is not just about transferring risk — it’s about understanding it.

    The most resilient businesses typically:

    • Review sums insured regularly
    • Assess realistic downtime scenarios
    • Understand dependencies across suppliers and customers
    • Identify operational bottlenecks
    • Build business continuity planning into decision-making
    • Align insurance cover with actual trading exposure

    The Health and Safety Executive also highlights the importance of managing workplace environmental risks, including heat stress, as part of broader operational safety planning.

    Is Your Cover Still Fit for Purpose?

    Periods of disruption often expose gaps that were not previously visible.

    That is why regular review is essential — not just at renewal, but whenever a business changes, invests, expands, or shifts its operating model.

    At Readhunt, we work with specialist businesses to help them understand their exposure, identify potential gaps, and design insurance programmes that support long-term resilience rather than minimum compliance.

    Because when everything is running smoothly, insurance feels routine.

    But when disruption arrives, it becomes one of the most important decisions a business has made.

    Contact the team on 01709 278 178 for a free insurance review.

  • Meet the Team: Spike Dolphin, Divisional Director, Readhunt London Markets

    Meet the Team: Spike Dolphin, Divisional Director, Readhunt London Markets

    As Readhunt London Markets continues to evolve, we’re introducing the people behind the business. First up is Spike Dolphin, Divisional Director, whose career in the Lloyd’s and wider London insurance markets spans more than a decade. We sat down with Spike to learn more about his journey into insurance, his vision for Readhunt and why relationships remain at the heart of everything he does.

    Tell us about your career journey

    Like many people, I never planned to end up in insurance.

    With a place at university confirmed, I decided to take some work experience during the summer to get a feel for working life before making a final decision. Two months later, I was offered a job and realised I would be better suited to spending three years learning on the ground rather than obtaining a degree.

    Ten years on, I can confidently say it was the right decision.

    Since starting my career in 2015, I’ve developed broad experience across the Lloyd’s and London markets, working with clients and underwriters across a range of classes. Throughout that time, I’ve built my approach around strong relationships, clear communication and finding practical solutions that create long-term value for clients.

    What is your vision for Readhunt London Markets?

    My vision is to build a brokerage that clients turn to regardless of market conditions.

    Insurance markets will always move through hard and soft cycles, but those factors are outside any broker’s control. What truly differentiates a business is its service, expertise and relationships.

    Our success comes from delivering an unrivalled level of service and maintaining strong, trusted relationships with both clients and insurer partners. By understanding our clients’ needs, providing honest advice and leveraging the right market connections, Readhunt can consistently deliver the solutions clients require whatever the market environment.

    The goal is simple: to be the first call our clients make because they know they will receive exceptional service, expert guidance and a team that will always go the extra mile on their behalf.

    How has the market changed since you began your career?

    Over the last decade, the market has continued to evolve through increased digitalisation and more efficient ways of trading business. However, one thing hasn’t changed: insurance remains a people business.

    Relationships with brokers, underwriters and clients are still fundamental, and the real differentiator is having the right team around you. The best outcomes are rarely achieved by one individual alone; they come from talented people working together, combining expertise, trust and a shared commitment to finding solutions.

    That’s what will continue to drive success in the years ahead.

    What qualities are most important in this industry?

    For me, it comes down to three things: trust, expertise and service.

    Clients need confidence that you understand their challenges and have access to the right solutions. Equally important is building lasting relationships with insurer partners and maintaining a collaborative approach.

    Ultimately, this industry is built on people, and reputation is everything.

    What do you enjoy outside work?

    Outside the office, you’ll usually find me on a golf course or a padel court.

    While both provide a welcome break from the day-to-day, I’ve always found they offer something more valuable too – an opportunity to build and strengthen relationships away from the trading floor. In an industry built on trust, some of the best conversations happen outside the office and those connections are often just as important as the deals themselves.

    Looking ahead

    I’m excited about what lies ahead for Readhunt London Markets.

    As we continue to grow, our focus will remain the same: building the right team, strengthening relationships and delivering the service and expertise that clients value most. Markets will continue to change, but by staying close to our clients and working collaboratively with our partners, we’ll continue to create solutions that stand the test of time.

    For more information about Readhunt London Markets, contact spike.dolphin@readhunt.co.uk.

  • Civil Engineering Insurance: Why Your Cover Needs to Match the Complexity of Your Work

    Civil Engineering Insurance: Why Your Cover Needs to Match the Complexity of Your Work

    Civil engineering insurance is complex – it is often the liability tail most businesses in the construction sector underestimate.

    A design error may not surface for years. A drainage failure that causes flooding three years after handover. Ground settlement that emerges during a subsequent development. By the time the claim arrives, the site is closed and the team has moved on. Generic construction cover – designed for shorter-duration build risk – often isn’t built for this.

    Professional indemnity: the cover that protects your expertise

    PI insurance protects against claims arising from design errors, specification mistakes, miscalculations, and negligent project oversight. For civil engineers it’s the most critical cover – and the most commonly undervalued.

    Policy limits typically range from £1 million to £10 million depending on contract values and tender requirements. Crucially, PI needs to be maintained for six to twelve years after project completion to cover the full window of liability exposure. Carrying insufficient limits can also disqualify you from tendering on major infrastructure contracts.

    Contractors’ all risks and plant cover

    Contract works insurance protects work in progress against fire, flood, theft, and accidental damage. The sum insured must reflect the full replacement value of works and materials at any point during the programme – not a figure set at the start and never revisited.

    Hired-in plant deserves specific attention. If equipment you’ve hired is damaged or stolen, you’re typically liable for the cost regardless of fault. With plant and machinery theft estimated to cost the construction sector £70 million annually, this isn’t a peripheral risk.

    Environmental liability

    Earthworks and excavation near watercourses, brownfield sites, or sensitive land create real environmental exposure. A fuel spill during construction can require costly remediation and trigger significant regulatory fines. Environmental liability insurance is increasingly considered standard for civil engineering operations – not an optional add-on.

    London market access for complex risks

    Some civil engineering risks can’t be placed adequately in the standard market. Readhunt has direct Lloyd’s broker registration, giving us access to specialist syndicates with the appetite and expertise to properly underwrite complex or high-value civil engineering risks. For firms working on major infrastructure programmes, that access makes a genuine difference.

    To talk through your insurance programme with a specialist team, call 01709 278178 or email us insurance@readhunt.co.uk

  • The Manufacturing Insurance Gap That Can Stop Production Overnight

    The Manufacturing Insurance Gap That Can Stop Production Overnight


    The assumption that catches manufacturers out with their manufacturing insurance

    Ask most manufacturing business owners if their premises and equipment are insured, and they’ll say yes. What fewer realise is that their standard commercial property policy likely does not cover the risk that poses the greatest operational threat to their business – machinery breaking down.

    It’s a common and costly misconception. Standard property insurance covers external events: fire, flood, storm, theft. It does not cover internal mechanical failure, electrical faults, or operator error. For a business whose entire output depends on production equipment running reliably, that’s a significant gap.

    What machinery breakdown insurance actually covers

    Machinery breakdown insurance – sometimes arranged as engineering breakdown cover – is designed for sudden and unforeseen failure of plant and equipment. That includes mechanical and electrical faults, motor and drive failures, control panel damage, and in many cases operator error.

    Critically, the repair cost is only part of the picture. Cover for the repair of the machine is only half the solution – the associated business interruption cover is often the more important element, kicking in to cover the financial loss resulting from downtime, including increased costs of working such as outsourcing, hiring replacement machinery, or paying overtime to clear backlogs once repairs are complete.

    For manufacturers operating to tight delivery schedules, this matters enormously. A critical machine down for two or three weeks doesn’t just cost the repair – it costs missed delivery slots, potential customer penalties, emergency outsourcing, and in some cases permanent damage to client relationships.

    The indemnity period problem

    One of the most common mistakes we see when reviewing manufacturing insurance programmes is an indemnity period that’s too short. The indemnity period is the length of time the insurer will pay for business interruption following a covered event. Many manufacturers set it at 12 months without considering how long a genuine worst-case scenario would take to fully recover from.

    For businesses that depend on specialist machinery with long lead times for parts or replacement – which describes a significant proportion of UK manufacturers – an indemnity period of 18 or 24 months is often more appropriate. Setting it too short means cover runs out before the business has fully recovered, leaving the gap to be absorbed internally.

    Product liability: the long tail most manufacturers underestimate

    Beyond machinery and property, product liability is the other area where manufacturing businesses frequently carry more risk than they realise.

    If a product you manufacture causes injury, property damage, or financial loss to a third party – whether a direct customer or an end user further down the supply chain – you can be held liable. Product liability claims can arise years after the product left your facility, involve multiple parties, and generate legal costs well before any compensation is determined. The financial exposure can be substantial, particularly for manufacturers supplying safety-related products, food and drink, industrial equipment, or components used in high-risk applications.

    It’s also worth checking that your product liability limits are appropriate for the contracts you’re working under. Larger clients increasingly specify minimum liability limits as a condition of supply – being underinsured here can affect your ability to retain or win business.


    A complete manufacturing insurance programme

    A well-structured programme for a UK manufacturer should typically include public liability, employers’ liability, product liability, material damage to premises and stock, machinery breakdown, business interruption with an appropriate indemnity period, and goods in transit for finished product and raw materials. Depending on the nature of the operation, additional covers – cyber liability, management liability, engineering inspection – may also be relevant.

    At Readhunt, we take the time to understand how a manufacturing business actually operates before recommending cover – the production processes, the critical assets, the contractual obligations, the supply chain. Generic policies rarely fit manufacturing well. Tailored ones do.

    If you’d like an honest review of your current manufacturing insurance programme, call us on 01709 278178 or visit readhunt.co.uk

  • 5 Most Common Insurance Claims Facing UK SMEs

    5 Most Common Insurance Claims Facing UK SMEs

    When businesses think about risk, they often picture rare, dramatic events. In reality, the insurance claims that hit UK small and medium-sized enterprises hardest are far more ordinary – and far more frequent. Understanding where claims most commonly arise is the first step to making sure your cover is working as hard as your business does.

    The 5 Most Common Insurance Claims for UK SMEs

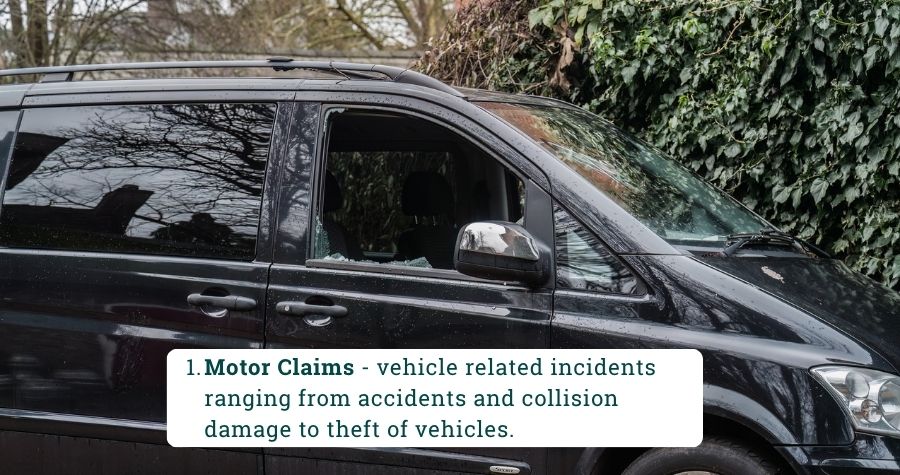
    1. Motor Claims

    Vehicle-related incidents are among the most frequent insurance claims for businesses that rely on a fleet or company vehicles. This covers everything from minor collisions and third-party damage through to vehicle theft. Whether you run a single van or a multi-vehicle fleet, adequate motor cover protects your mobility and your bottom line.

    2. Property Damage

    Fires, floods, burst pipes, and accidental damage to premises or equipment can strike any business at any time. Property damage claims can be significant – not just in repair costs, but in lost productivity while operations are disrupted. Ensuring your buildings and contents are accurately valued is critical to a swift recovery.

    3. Liability Claims

    Liability claims span a wide range: public liability (injuries to customers or third parties), product liability (harm caused by goods you supply), professional indemnity (errors in advice or services), and employers’ liability (workplace injuries to staff). Any of these can lead to costly legal proceedings without the right protection in place.

    4. Cyber Incidents

    Cyber threats are a growing reality for UK SMEs. Data breaches, ransomware attacks, and phishing scams can cripple operations, damage customer trust, and trigger regulatory penalties. Cyber insurance has moved from a niche product to an essential layer of protection for businesses of all sizes.

    5. Business Interruption

    When operations grind to a halt – due to a covered loss, a supplier failure, or an unexpected disruption – the financial consequences can mount quickly. Business interruption insurance replaces lost income during downtime, giving you the breathing room to recover without draining your reserves.

    Why the Right Cover Changes Everything

    Having insurance is one thing – having insurance that actually fits your business is another.

    When your cover is tailored to your specific operations, sector, and risk profile, claims become manageable rather than catastrophic. The right policy means:

    • No coverage gaps that slow down or complicate your claim
    • Faster recovery because your insurer understands your business
    • Less stress when incidents occur, so you can focus on getting back to work

    How Readhunt Helps UK SMEs Stay Protected

    At Readhunt, we combine sector-specific expertise with efficient claims management. From construction and logistics to manufacturing and engineering, we guide SMEs through every step of the process – making claims smoother, faster, and less disruptive.

    We don’t believe in one-size-fits-all policies. We take the time to understand your operations, your sector risks, and your exposures, so you’re never over-insured, under-insured, or caught out.

    Tailored solutions. Appropriate insurance. Expert claims support. That’s how SMEs stay resilient.

    If you need to review your coverage, contact us on 01709 278178 or email us info@readhunt.co.uk